Withholding Tax Table 2026: How Cafés Compute Staff Tax
By Robin Salvador, co-founder, Caffeine Brothers
Last updated: November 17, 2026
Quick answer: The withholding tax table for 2026 is the same one employers have used since January 1, 2023 (Annex E of BIR Revenue Regulations No. 11-2018). On the monthly table, taxable pay of ₱20,833 or less has no withholding. The rate is 15% of the excess over ₱20,833 up to ₱33,332, then ₱1,875 plus 20% over ₱33,333, and so on up to 35% above ₱666,667. Taxable pay means gross pay minus the employee’s SSS, PhilHealth and Pag-IBIG shares and other non-taxable items. Minimum wage earners are exempt.
Key takeaways
- The 2023 table still applies in 2026. We found no BIR regulation that replaces it for compensation; the 2025 to 2026 withholding changes (RR 24-2025) cover payments to suppliers, not salaries.
- Monthly brackets: ₱0 up to ₱20,833; 15%, 20%, 25%, 30% and 35% above that, matching the annual rates in RA 10963 for 2023 onwards.
- A café crew member paid the NCR minimum of ₱718 or ₱755 a day (Wage Order NCR-28, effective September 26, 2026) has no tax withheld on that pay.
- At ₱25,000 a month, withholding is ₱313.80 after mandatory contributions. At ₱35,000 it is ₱1,701.30.
- A House bill raising the tax-free threshold to ₱350,000 passed committee on August 10, 2026, but it is not law. The earliest start lawmakers mentioned is January 1, 2027.
Every employer that pays salaries in the Philippines, including a small coffee shop with two or three baristas, is a withholding agent. You deduct income tax from each payroll, remit it to the BIR every month and give each employee a certificate at year end. This guide sets out the 2026 tables, shows the computation for common café and office salaries, and lists the year-end deadlines. Amounts were checked on November 17, 2026.
What is the withholding tax table for 2026?
The tax rates come from Section 24(A)(2) of the National Internal Revenue Code as amended by RA 10963 (the TRAIN law). Its “Tax Schedule Effective January 1, 2023 and onwards” taxes the first ₱250,000 of annual taxable income at 0%, the next band up to ₱400,000 at 15% of the excess over ₱250,000, then ₱22,500 plus 20% up to ₱800,000, ₱102,500 plus 25% up to ₱2,000,000, ₱402,500 plus 30% up to ₱8,000,000, and ₱2,202,500 plus 35% above that.
When those rates took effect, the BIR told employers to use “the revised withholding tax table” beginning January 1, 2023 (GMA News, December 23, 2022). Vialto Partners reproduced the table in its December 2024 year-end reminders, and the Supreme Court’s Office of the Court Administrator used the same figures in OCA Circular No. 35-2024. The two copies match. We searched for a newer table for 2026 and found none, so the table below still applies.
| Monthly taxable compensation | Tax to withhold | Rate on the excess |
|---|---|---|
| ₱20,833 and below | ₱0 | 0% |
| ₱20,833 to ₱33,332 | ₱0 + 15% of the excess over ₱20,833 | 15% |
| ₱33,333 to ₱66,666 | ₱1,875.00 + 20% of the excess over ₱33,333 | 20% |
| ₱66,667 to ₱166,666 | ₱8,541.80 + 25% of the excess over ₱66,667 | 25% |
| ₱166,667 to ₱666,666 | ₱33,541.80 + 30% of the excess over ₱166,667 | 30% |
| ₱666,667 and above | ₱183,541.80 + 35% of the excess over ₱666,667 | 35% |
If you pay twice a month, use the semi-monthly table. Most cafés pay on the 15th and the end of the month, so this is the table a small shop is most likely to need.
| Semi-monthly taxable compensation | Tax to withhold |
|---|---|
| ₱10,417 and below | ₱0 |
| ₱10,417 to ₱16,666 | ₱0 + 15% over ₱10,417 |
| ₱16,667 to ₱33,332 | ₱937.50 + 20% over ₱16,667 |
| ₱33,333 to ₱83,332 | ₱4,270.70 + 25% over ₱33,333 |
| ₱83,333 to ₱333,332 | ₱16,770.70 + 30% over ₱83,333 |
| ₱333,333 and above | ₱91,770.70 + 35% over ₱333,333 |
| Rate band | Daily taxable compensation | Weekly taxable compensation |
|---|---|---|
| 0% | ₱685 and below | ₱4,808 and below |
| 15% | ₱685 to ₱1,095: ₱0 + 15% over ₱685 | ₱4,808 to ₱7,691: ₱0 + 15% over ₱4,808 |
| 20% | ₱1,096 to ₱2,191: ₱61.65 + 20% over ₱1,096 | ₱7,692 to ₱15,384: ₱432.60 + 20% over ₱7,692 |
| 25% | ₱2,192 to ₱5,478: ₱280.85 + 25% over ₱2,192 | ₱15,385 to ₱38,461: ₱1,971.20 + 25% over ₱15,385 |
| 30% | ₱5,479 to ₱21,917: ₱1,102.60 + 30% over ₱5,479 | ₱38,462 to ₱153,845: ₱7,740.45 + 30% over ₱38,462 |
| 35% | ₱21,918 and above: ₱6,034.30 + 35% over ₱21,918 | ₱153,846 and above: ₱42,355.65 + 35% over ₱153,846 |
Coffee beans for your café
Caffeine Brothers supplies cafés, offices and restaurants with freshly roasted Philippine coffee in 10 kg wholesale boxes from ₱773/kg, with free Metro Manila delivery and a free sample before you commit.
See Wholesale Prices →What counts as taxable pay?
You apply the table to taxable compensation, not to gross pay. Several items come off first.
- Employee shares of SSS, PhilHealth and Pag-IBIG contributions and union dues are excluded under Section 32(B)(7)(f) of the Tax Code. For the 2026 amounts see our guides to the SSS contribution table, PhilHealth contributions and Pag-IBIG contributions.
- The 13th month pay and “other benefits such as productivity incentives and Christmas bonus” are excluded up to a total of ₱90,000 a year under Section 32(B)(7)(e).
- De minimis benefits within the ceilings of RR 29-2025, effective January 6, 2026: for example rice up to ₱2,500 a month, uniform allowance up to ₱8,000 a year, laundry up to ₱400 a month and Christmas gifts up to ₱6,000 a year (P&A Grant Thornton, January 19, 2026).
- For minimum wage earners, the statutory minimum wage, holiday pay, overtime pay, night shift differential and hazard pay.
Anything else you pay, such as a monthly allowance above the de minimis limits, commissions or a service charge share, is taxable compensation and goes through the table.
Do minimum wage earners pay withholding tax?
No, on their minimum wage. RA 9504 added this to the Tax Code: “minimum wage earners … shall be exempt from the payment of income tax on their taxable income,” and “the holiday pay, overtime pay, night shift differential pay and hazard pay received by such minimum wage earners shall likewise be exempt from income tax.” Section 79(A) also excludes minimum wage earners from the employer’s duty to withhold on wages.
Under Wage Order NCR-28, which took effect on September 26, 2026, the Metro Manila minimum went from ₱695 to ₱755 a day for most non-agriculture workers, and from ₱658 to ₱718 for retail and service establishments with 15 workers or fewer (GMA News, September 26, 2026). At 313 paid days a year, ₱718 a day is about ₱18,727.83 a month and ₱755 is about ₱19,692.92. Both are below the ₱20,833 line anyway, but the exemption matters when a minimum wage barista also earns holiday or overtime pay.
A minimum wage earner who receives other taxable income from you, such as a commission or an allowance above the de minimis limit, is still exempt on the minimum wage and its premiums. Only the other income goes through the table (Deloitte, “Tax in a Dot,” March 21, 2018, on RR 11-2018). In practice a small monthly commission on its own stays under ₱20,833, so nothing is withheld, but it still has to be reported on the employee’s BIR Form 2316.
How do you compute withholding tax for a café employee?
- Start with gross monthly pay for the period: basic pay plus any taxable allowances, commissions and premiums.
- Subtract non-taxable items: the employee’s SSS, PhilHealth and Pag-IBIG shares, de minimis benefits within the limits, and the 13th month and bonuses up to ₱90,000 for the year.
- Find the bracket for the result in the monthly, semi-monthly, weekly or daily table that matches your payroll schedule.
- Apply the formula: the fixed amount for the bracket plus the rate times the excess over the bracket’s lower limit.
- Remit by the deadline using BIR Form 1601-C, and keep the payroll record for the year-end annualization.
Here is the computation for a café supervisor paid ₱25,000 a month. The SSS employee share is ₱1,250 (SSS Circular No. 2024-006 schedule for the ₱24,750 to ₱25,249.99 bracket). PhilHealth is 5% of ₱25,000, split equally, so ₱625 (PhilHealth Advisory No. 2026-0042). Pag-IBIG is 2% of pay up to the ₱10,000 maximum fund salary, so ₱200 (HDMF Circular No. 460 via Forvis Mazars, January 25, 2024). Taxable pay is ₱25,000 − ₱1,250 − ₱625 − ₱200 = ₱22,925. That falls in the 15% band: (₱22,925 − ₱20,833) × 15% = ₱313.80 a month.
| Gross monthly pay | Employee SSS / PhilHealth / Pag-IBIG | Monthly taxable pay | Tax withheld per month |
|---|---|---|---|
| ₱18,727.83 (₱718 a day, minimum wage earner) | Not needed | Exempt | ₱0 |
| ₱20,000 | ₱1,000 / ₱500 / ₱200 | ₱18,300.00 | ₱0 |
| ₱25,000 | ₱1,250 / ₱625 / ₱200 | ₱22,925.00 | ₱313.80 |
| ₱30,000 | ₱1,500 / ₱750 / ₱200 | ₱27,550.00 | ₱1,007.55 |
| ₱35,000 | ₱1,750 / ₱875 / ₱200 | ₱32,175.00 | ₱1,701.30 |
| ₱50,000 | ₱1,750 / ₱1,250 / ₱200 | ₱46,800.00 | ₱4,568.40 |
| ₱80,000 | ₱1,750 / ₱2,000 / ₱200 | ₱76,050.00 | ₱10,887.55 |
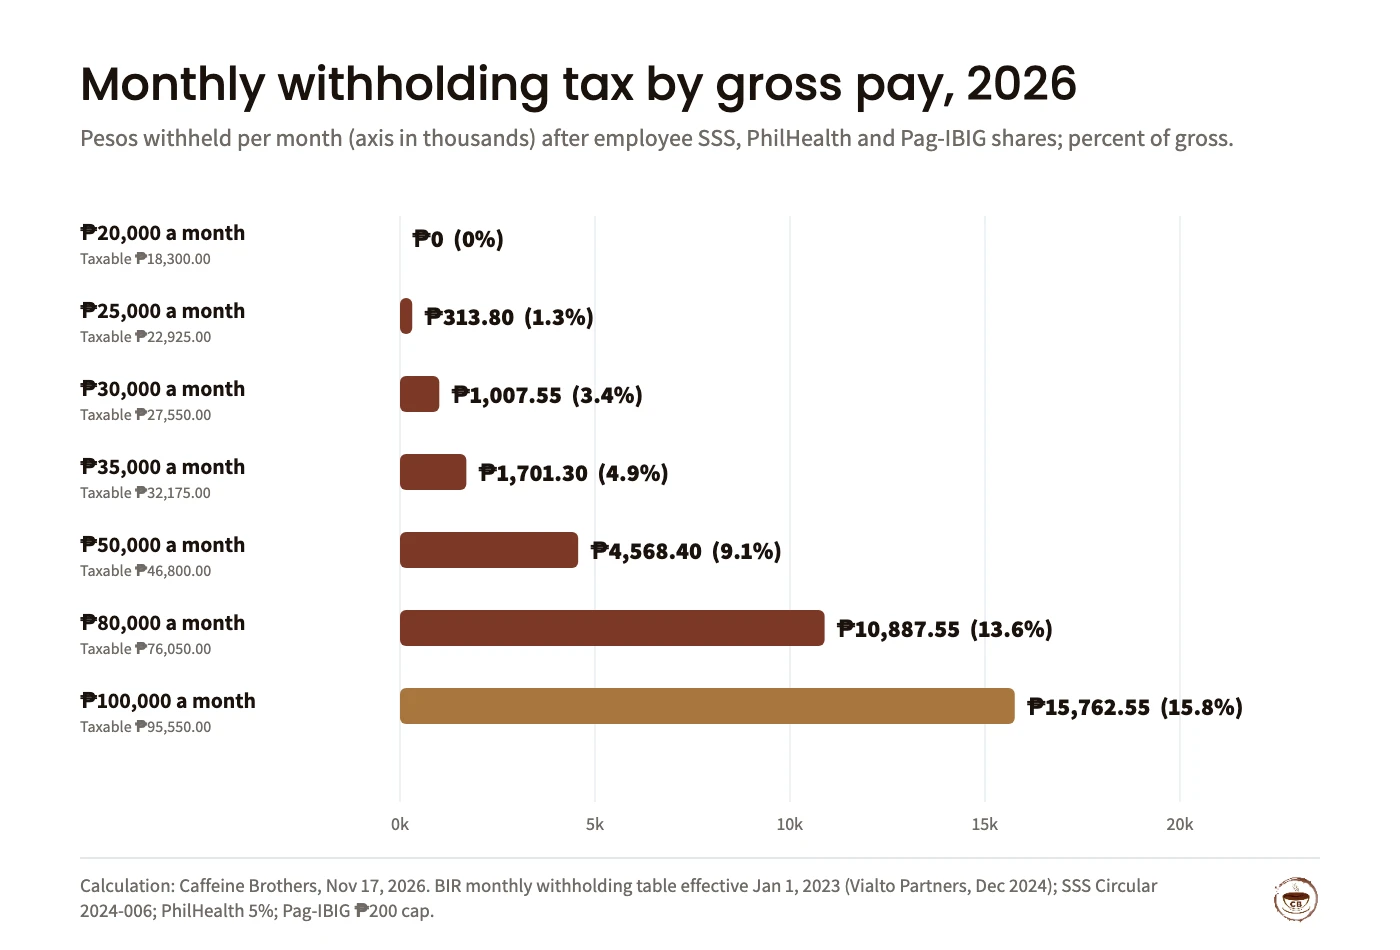
The chart shows how gently the tax starts. A ₱30,000 salary loses about 3.4% of gross pay to withholding, and a ₱50,000 salary about 9.1%. The top rates only apply to the part of pay inside each band.
What happens at year end?
Each December the employer annualizes: it adds up the year’s taxable compensation, computes the tax on the annual rates and compares it with what was withheld. Any shortfall comes out of the December pay, and any over-withholding must be refunded “no later than January 25 of the following year” (Vialto Partners, December 11, 2025). Because the monthly table rounds ₱250,000 ÷ 12 down to ₱20,833, the true-up is often a few centavos. For the ₱25,000 example, twelve months at ₱313.80 is ₱3,765.60, while the annual tax on ₱275,100 is ₱3,765.00.
The 13th month pay is where cafés most often get this wrong. A ₱35,000 manager who receives a ₱35,000 13th month pay and a ₱20,000 Christmas bonus gets ₱55,000 in total, which is under the ₱90,000 ceiling, so none of it is taxed. Our 13th month pay guide and Christmas bonus guide cover the rules in more detail.
| Filing or payment | Deadline |
|---|---|
| BIR Form 1601-C for November 2026 (manual or non-eFPS) | December 10, 2026 (Thursday) |
| BIR Form 1601-C for November 2026 (eFPS) | E-filing December 11 to 15 by group; e-payment December 15 |
| BIR Form 1601-C for December 2026 (manual or non-eFPS) | January 15, 2027 (Friday) |
| BIR Form 1601-C for December 2026 (eFPS) | E-filing staggered to January 15; e-payment January 20, 2027 |
| Refund of over-withheld tax after year-end annualization | No later than January 25, 2027 (Monday) |
| BIR Form 2316 to employees, and BIR Form 1604-C with the alphalist | January 31 of the following year. January 31, 2027 is a Sunday; in 2026 the BIR deadline moved to the next working day. |
| Scanned signed 2316s of employees under substituted filing | February 28 of the following year (also a Sunday in 2027) |
Employees who earned purely compensation income from one employer during the year, and whose tax withheld equals their tax due, qualify for substituted filing: their BIR Form 2316 takes the place of an annual income tax return (Vialto Partners, December 11, 2025). The Ease of Paying Taxes Act (RA 11976, effective January 22, 2024) also lets you file and pay at any district office, authorized agent bank or through a tax software provider.
Will the tax-free threshold rise to ₱350,000?
Possibly, but not for 2026. In his July 27, 2026 State of the Nation Address the President proposed raising the ₱250,000 threshold to ₱350,000. House Bill No. 10345 does this, and the House Ways and Means Committee approved it on August 10, 2026 (GMA News). The Department of Finance said the number of compensation earners exempt from income tax would rise from 5.1 million to 6.35 million. BusinessWorld (October 1, 2026) estimated the saving at about ₱15,000 a year for someone earning ₱350,000 or more.
Several Senate bills propose ₱350,000 or more, including SB 2338 starting July 1, 2027, SB 2341 at ₱600,000 and SB 2344 (Manila Times, August 1, 2026). Rep. Miro Quimbo said the earliest possible start is January 1, 2027 (DZRH, July 28, 2026). We found no report of the bill being enacted as of November 17, 2026, so keep using the 2023 table and update your payroll only after a law and new BIR table are issued.
Frequently asked questions
Is there a new withholding tax table for 2026?
No new table has been issued for compensation. Employers still use the table in Annex E of Revenue Regulations No. 11-2018, which took effect on January 1, 2023. It follows the income tax rates that RA 10963 set for 2023 onwards.
How much salary is tax-free in the Philippines in 2026?
Annual taxable income up to ₱250,000 is taxed at 0%. On the monthly table that is ₱20,833 of taxable pay, which is pay after the employee’s SSS, PhilHealth and Pag-IBIG shares. Minimum wage earners are exempt on their statutory minimum wage, holiday pay, overtime pay, night shift differential and hazard pay.
Is the 13th month pay taxed?
The 13th month pay and other benefits such as productivity incentives and a Christmas bonus are excluded from taxable income up to ₱90,000 a year in total under Section 32(B)(7)(e) of the Tax Code. Only the part above ₱90,000 is taxed.
Will the ₱350,000 tax-free threshold apply in 2026?
No. House Bill No. 10345, which would raise the threshold to ₱350,000, was approved by the House Ways and Means Committee on August 10, 2026. Lawmakers said January 1, 2027 is the earliest start. Until a law is enacted, the ₱250,000 threshold and the 2023 table apply.
Sources
- Republic Act No. 10963 (TRAIN law). LawPhil, approved December 19, 2017. Tax schedule effective January 1, 2023; Section 32(B)(7)(e) ₱90,000 exclusion
- Republic Act No. 9504. LawPhil, approved June 17, 2008. Minimum wage earner exemption, Sections 22(HH) and 79(A)
- Republic Act No. 8424 (National Internal Revenue Code). LawPhil. Section 32(B)(7)(f) exclusion of SSS, PhilHealth and Pag-IBIG contributions
- 2024 year-end reminders on employment taxes. Vialto Partners, December 4, 2024. Daily, weekly, semi-monthly and monthly withholding tables effective January 1, 2023
- OCA Circular No. 35-2024. Supreme Court Office of the Court Administrator, February 5, 2024. Same withholding tables (scanned document)
- Lower income tax rates to greet taxpayers next year: BIR. GMA News, December 23, 2022. Revised table from January 1, 2023
- 2025 year-end reminders on employment and individual taxes. Vialto Partners, December 11, 2025. Annualization, refund by January 25, 2316 and 1604-C deadlines, substituted filing
- 2026 December tax calendar. PwC Philippines. 1601-C dates for November 2026
- Tax in a Dot: amendments to the withholding tax regulations. Deloitte Philippines, March 21, 2018. RR 11-2018 rules for minimum wage earners with other income
- Updated de minimis benefits threshold. P&A Grant Thornton, January 19, 2026. RR 29-2025 ceilings, effective January 6, 2026
- Ease of Paying Taxes Act introduces key administrative tax reforms. Vialto Partners, January 30, 2024. RA 11976 filing venues, effective January 22, 2024
- BIR clears confusion over revised withholding tax rules. Context.ph, July 21, 2026. RR 24-2025 and RMC 79-2026 cover creditable withholding, not compensation
- DOLE: P60 wage hike in NCR takes effect Sept. 26. GMA News, September 26, 2026. Wage Order NCR-28 rates
- SSS contribution table (Circular No. 2024-006). Social Security System, effective January 2025, read November 17, 2026. Employee shares by salary bracket
- PhilHealth Advisory No. 2026-0042. PhilHealth, 2026. 5% premium rate, ₱10,000 floor and ₱100,000 ceiling
- Pag-IBIG increases the maximum fund salary. Forvis Mazars, January 25, 2024. HDMF Circular No. 460, ₱10,000 maximum fund salary
- House panel approves raising tax-free income threshold to P350,000. GMA News, August 10, 2026. HB 10345 committee approval, DOF estimates
- Is real tax relief finally here? A look inside House Bill No. 10345. BusinessWorld, October 1, 2026. Estimated saving of about ₱15,000 a year
- Senate bill filed to raise income tax exemption to ₱350k. The Manila Times, August 1, 2026. Senate proposals
- Earliest possible implementation of tax exemption adjustment may begin on January 2027. DZRH, July 28, 2026. Planned start date
This article is general information about Philippine withholding tax rules as of November 17, 2026, not tax advice. Confirm your figures with your accountant or the BIR, especially for employees with several employers or non-standard pay.
Cite this article: Caffeine Brothers. “Withholding Tax Table 2026: How Cafés Compute Staff Tax.” Caffeine Brothers Coffee Blog, November 2026. https://caffeinebrothers.co/withholding-tax-table-2026/
You are welcome to reference the charts and tables in this article with a link back to this page.
Giving staff a Christmas gift this year? Gifts up to ₱6,000 per employee are tax-free de minimis benefits in 2026, and our Christmas coffee gift sets start at ₱120. For the pantry, wholesale 10 kg boxes come with free delivery in Metro Manila. Contact us for a bulk quote.
 Previous Post
 Next Post